
Introduction
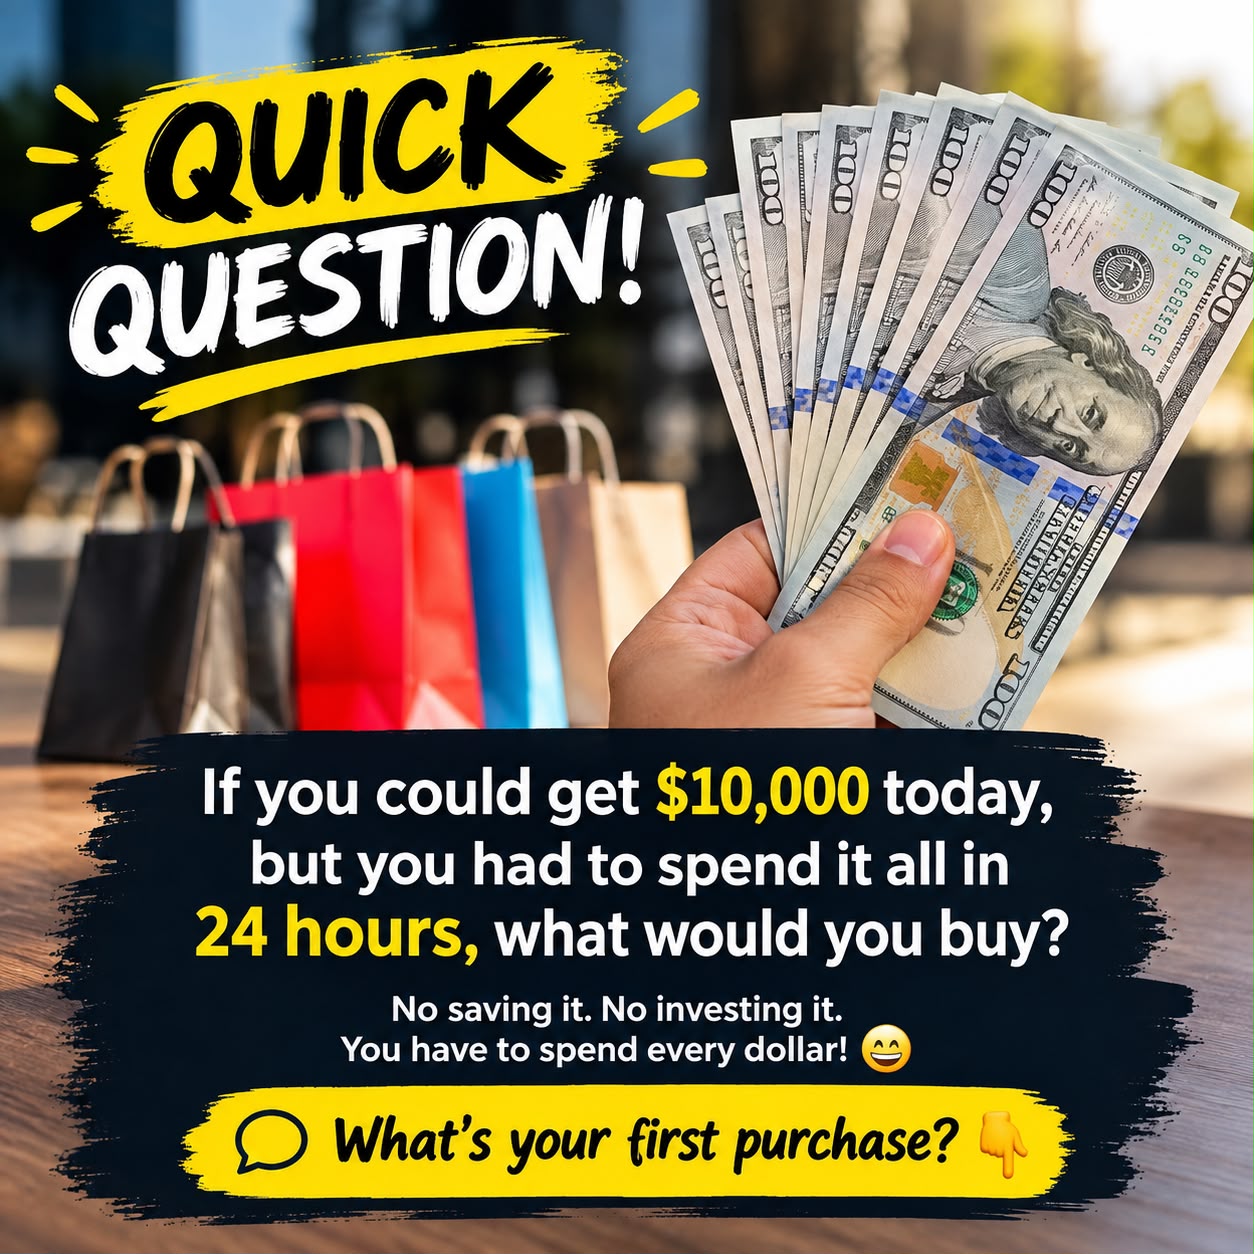
Interactive social media questions and financial hypotheticals frequently circulate online, offering fun scenarios to spark lively community discussions. When an engaging graphic appears asking what you would buy if you received $10,000 today with the strict rule to spend every dollar within 24 hours without saving or investing, it instantly catches the attention of readers eager to share their dream purchases.
Navigating personal finance, understanding budgeting, and adopting sound economic habits are essential parts of proper financial wellness. Furthermore, relying on disciplined savings and strategic planning rather than impulsive spending ensures long-term financial security. This comprehensive guide explores the realities of budgeting, spending psychology, and evidence-based financial management.
The Reality of Financial Windfalls: What Science Says
Receiving a sudden financial windfall or managing discretionary funds requires careful planning, budgeting, and long-term financial foresight rather than impulsive consumption.
Why Impulsive Spending Scenarios Are Just for Fun
While viral hypothetical questions encourage playful imagination about luxury items, travel, or immediate shopping sprees, actual financial windfalls are best handled with a strategic approach. Allocating unexpected funds toward emergency savings, high-interest debt reduction, or thoughtful investments provides lasting security compared to rapid, uncalculated spending.
The Importance of Long-Term Financial Planning
Achieving financial health involves consistent budgeting, building emergency funds, avoiding unnecessary debt, and making informed purchasing decisions guided by personal financial goals.
Practical Tips for Managing Money Wisely
Handling unexpected money and maintaining a healthy financial life involves reliable, evidence-based habits:
- Create a Solid Budget: Track your income and expenses carefully to ensure your money aligns with your priorities and needs.
- Build an Emergency Fund: Set aside savings to cover unexpected life events or financial emergencies securely.
- Prioritize Debt Reduction: Pay off high-interest debts before allocating funds toward non-essential discretionary purchases.
- Consult Financial Professionals: Speak with a certified financial planner for personalized advice on long-term wealth management.
- Be Skeptical of Impulse Buying: Pause and evaluate whether a purchase is truly necessary before spending discretionary funds.
Interesting Facts About Financial Psychology and Spending
- Behavioral economics shows that people often experience immediate psychological gratification when making quick purchases, followed by potential buyer’s remorse.
- Financial literacy is a key determinant of long-term economic stability, helping individuals navigate saving, credit, and investment opportunities effectively.
- Emergency savings act as a critical financial buffer, reducing stress and protecting households from sudden economic disruptions.
- Social media engagement thrives on hypothetical spending scenarios because they allow users to dream freely and share personal aspirations with others.
Conclusion
While viral social media questions use playful financial hypotheticals to drive community engagement, managing money effectively relies on disciplined budgeting, strategic savings, and long-term planning rather than impulsive spending sprees. By prioritizing financial wellness and thoughtful decision-making, you can secure your economic future. Relying on grounded financial strategies ensures true monetary stability.
Frequently Asked Questions (FAQ)
Is it wise to spend a financial windfall immediately?
No, financial experts generally recommend pausing, paying off high-interest debt, and saving a significant portion of unexpected funds rather than spending impulsively.
Why are hypothetical spending questions so popular online?
They spark imagination, encourage interactive community discussions, and allow people to playfully explore their dream purchases without real-world consequences.
What are the core components of good personal finance?
Essential components include consistent budgeting, emergency savings, disciplined debt management, and intentional, goal-oriented spending.
When should I seek professional financial advice?
You should consult a financial advisor when navigating major life transitions, retirement planning, complex investments, or significant debt reduction.
